The call begins with something manageable. Your mother cannot get into the patient portal. Your father has received a bill he does not recognize. The pharmacy needs authorization, the doctor’s office cannot speak to you and the password hint appears to refer to a pet last seen in 1987.
This is caregiving now: affection, logistics and approximately fourteen security questions.
The invisible job has become enormous
AARP’s 2025 national caregiving research found that one in four U.S. adults provided care to an adult or child with a complex medical condition or disability. Three in five caregivers were women, the average caregiver was 51 and nearly three in ten were also raising children. Federal Reserve research likewise found women more likely than men to provide unpaid adult care.
Those numbers include obvious tasks—rides, meals and hands-on help—and the administrative work that often goes unnamed: coordinating appointments, appealing charges, tracking medications, spotting scams and explaining the same situation to a new person in every department.
“Call me if you need anything” works better when everyone knows where “anything” is kept.
Start with permission, not passwords
It may be tempting to collect every login in a notebook. A safer first step is to learn what formal access is available. Health systems may offer proxy portal access. Banks and investment firms may have trusted-contact or power-of-attorney procedures. A durable financial power of attorney can allow a chosen person to act if needed, but the rules and documents vary by state and institution.
The Consumer Financial Protection Bureau offers guides for people managing someone else’s money and recommends planning before illness or diminished capacity creates a crisis. A password alone does not create legal authority—and using another person’s login can create security and access problems.
Make the one-page version
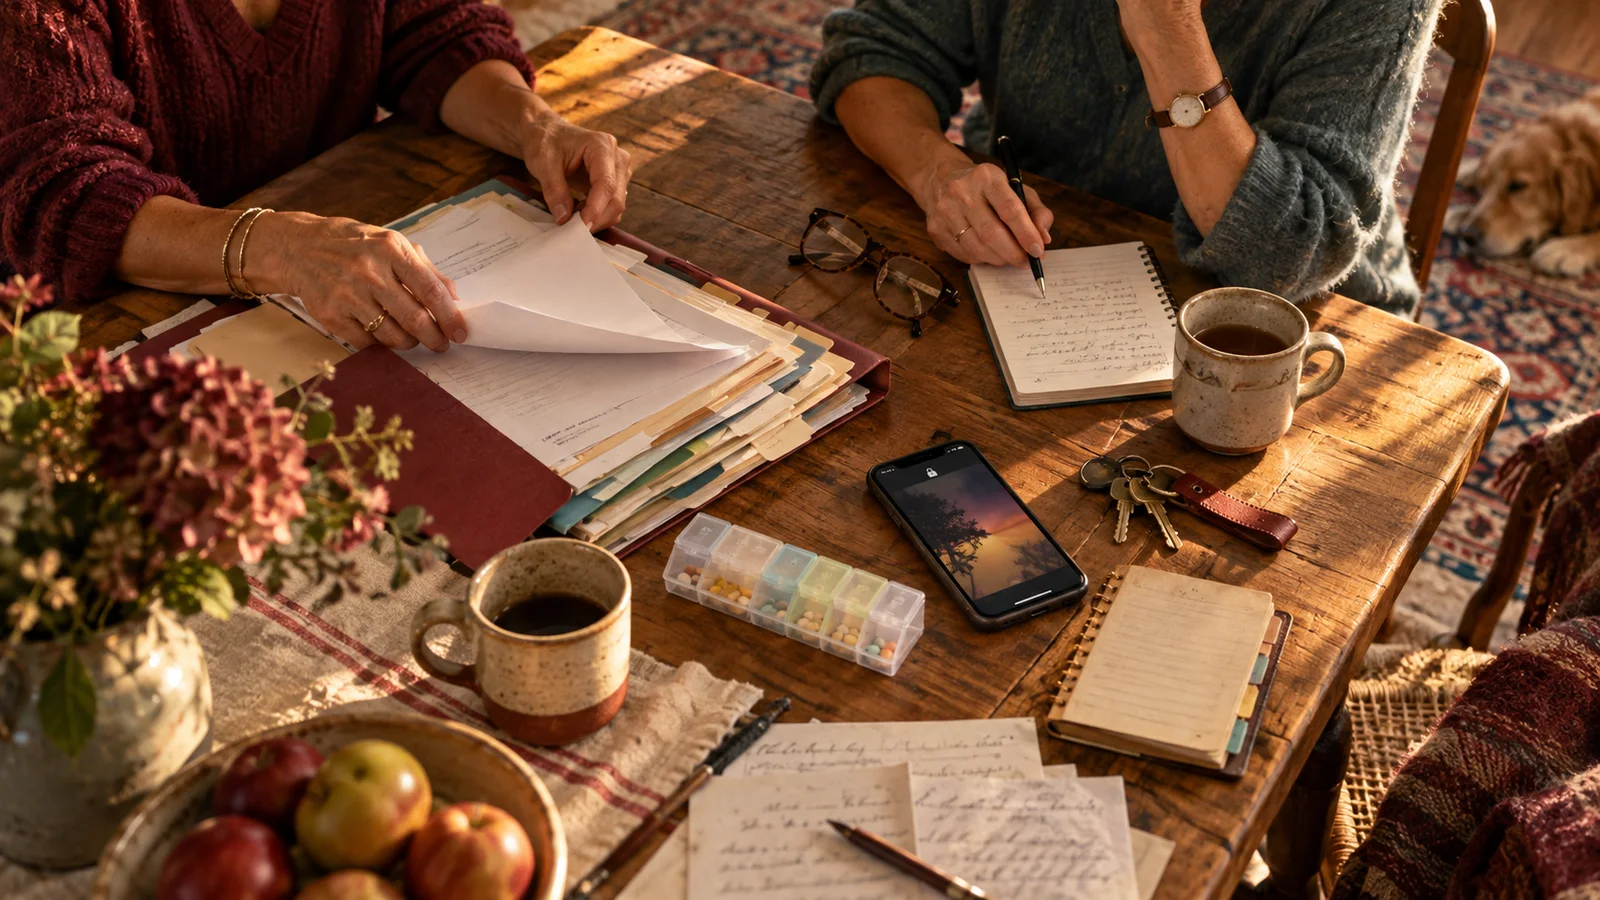
Create a single sheet with the information most likely to be needed quickly: primary clinicians, pharmacy, medications and allergies, insurance, emergency contacts, where legal documents are stored and which family member handles which job. Record account institutions, not full account numbers. Keep the document protected and tell the right people where it is.
Then build the longer folder behind it. Include copies or locations of advance directives and powers of attorney, a current medication list, a bill calendar, property and insurance contacts and notes from major conversations. Review it twice a year or after a hospital stay, medication change, move or loss.
Give the family actual assignments
One sibling saying “tell me what to do” can be useful if the answer is specific. Assign lanes: medical notes, groceries, finances, transportation, home maintenance or weekly calls. Put decisions in a shared, secure record so the person doing the daily work does not also have to issue a family newsletter.
If one person is carrying most of the load, name that reality. A quarter of caregivers in AARP’s report said they had taken on debt. Care affects time, paid work and health. The family budget should treat it as a real responsibility, not a personality trait belonging to the most organized daughter.
Add fraud to the care plan
The Federal Trade Commission has reported steep growth in large-dollar losses from impersonation scams targeting older adults. Decide in advance that no urgent caller, text or email gets money, gift cards, cryptocurrency, remote computer access or personal information without a pause and a second call using a known number.
The goal is not to seize control. It is to make support possible while preserving as much independence and dignity as circumstances allow. One folder will not make aging simple. It can, however, prevent a bad Tuesday from becoming a full administrative collapse.
Editorial note: Legal and financial authority varies by jurisdiction and institution. Consult qualified legal, financial and health professionals for advice about your family’s situation.
Sources
AARP: Caregiving in the U.S. 2025
Federal Reserve: Care Work and Living Arrangements
CFPB: Managing Someone Else’s Money
FTC: Impersonation scam losses among older adults